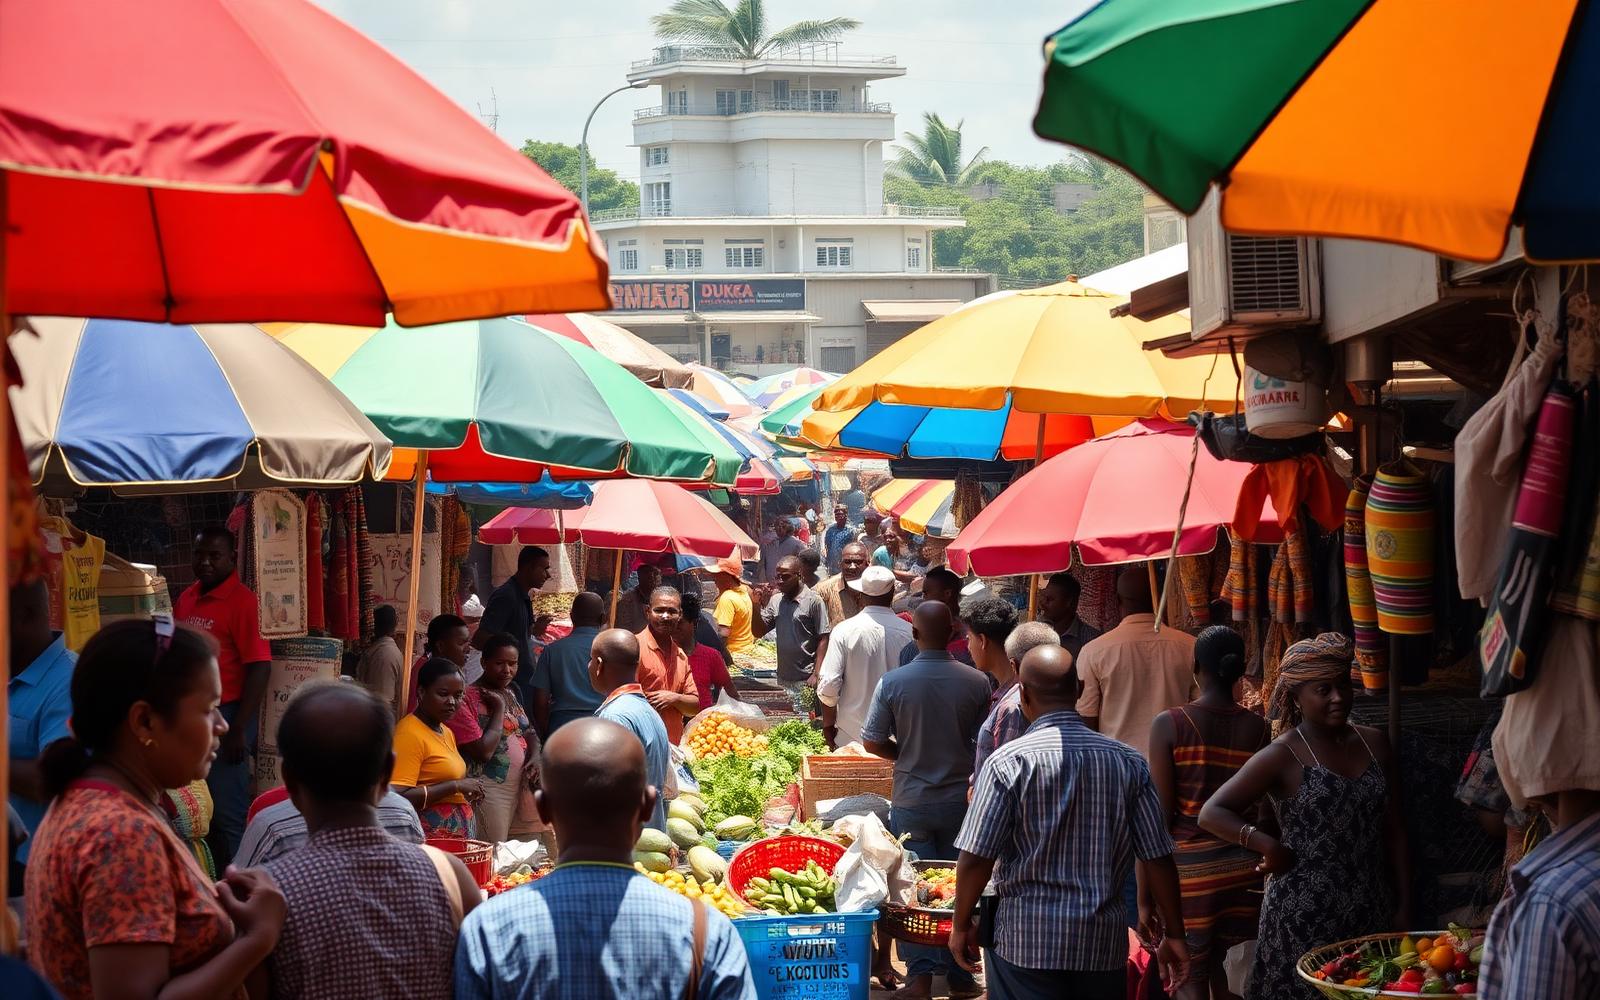
The Informal Economy Is Not Unstructured: AI for African Retail's Real Backbone
Calling African retail informal has been an excuse to avoid understanding it. The patterns are extremely consistent, they are simply not in anyone's database.
Calling African retail informal has been an excuse to avoid understanding it. Open-air markets, dukas, and kiosks run on extremely consistent patterns, weekly price cycles, payday demand spikes, school-term and harvest seasonality, and trade credit relationships with rules stricter than most bank covenants.
That is structure. It simply is not in anyone's database.
Forecasting becomes tractable once the patterns are captured
For a distributor's kiosk network, demand forecasting at the outlet level is achievable with a season of clean sell-through data. The value shows up as fewer stockouts and less spoilage, not as a dashboard, and in fast-moving consumer goods those two lines are where the margin actually is.
The capture problem is the whole problem. Sell-through data exists only where the distributor's rep records it, which means route app design and rep incentives determine data quality far more than any modelling choice.
Any inventory tool that requires a shopkeeper to maintain a stock master is a spreadsheet exercise disguised as a product.
Fit the tool to the operator, not the operator to the tool
A shopkeeper will use a USSD prompt or a WhatsApp reorder nudge. They will not use an ERP, will not maintain a stock master, and will not log in daily to a portal. Any inventory intelligence that requires those behaviours is a spreadsheet exercise disguised as a product.
The corollary is that the interface budget matters more than the model budget, and that local language, low-literacy-tolerant flows are functional requirements.
The largest prize is digitising trade credit
Informal ledgers already encode years of repayment behaviour that no credit bureau has ever seen. A distributor who has extended and recovered stock credit with the same three hundred outlets for a decade holds an underwriting dataset of real value.
The right sequence is to instrument the ledger already being touched, deliveries, credit extended, days to settle, and only then to lend or partner with a lender against it. Attempting to originate credit before the ledger is structured reliably produces losses that end the programme.
What this means in practice
- Instrument outlet-level sell-through through the route app before commissioning any demand model.
- Deliver reorder intelligence over USSD or WhatsApp in local language, and abandon portal-based designs.
- Structure the trade credit ledger you already operate, credit extended, days to settle, recovery, as a first-class dataset.
- Underwrite only after a full seasonal cycle of structured ledger data, not before.
Frequently asked questions
- What is this analysis about?
- Calling African retail informal has been an excuse to avoid understanding it. The patterns are extremely consistent, they are simply not in anyone's database.
- What is the core argument?
- Calling African retail informal has been an excuse to avoid understanding it. Open-air markets, dukas, and kiosks run on extremely consistent patterns, weekly price cycles, payday demand spikes, school-term and harvest seasonality, and trade credit relationships with rules stricter than most bank covenants.
- Forecasting becomes tractable once the patterns are captured?
- For a distributor's kiosk network, demand forecasting at the outlet level is achievable with a season of clean sell-through data. The value shows up as fewer stockouts and less spoilage, not as a dashboard, and in fast-moving consumer goods those two lines are where the margin actually is.
- What should our organisation do about it?
- Instrument outlet-level sell-through through the route app before commissioning any demand model. Deliver reorder intelligence over USSD or WhatsApp in local language, and abandon portal-based designs. Structure the trade credit ledger you already operate, credit extended, days to settle, recovery, as a first-class dataset. Underwrite only after a full seasonal cycle of structured ledger data, not before.
- Who published this and can we discuss it with Kwish?
- Kwish Research Team at Kwish Technologies published this on May 2026. Kwish works on retail & trade programmes from offices in Uganda, Kenya, Sweden and Canada, and you can reach the team at info@kwishtechnologies.com.
Keep exploring
Turn this analysis into delivery
The services, sectors and case studies connected to this article.
Services that deliver this
Sectors where this applies
Related insights
Why African Governments Need AI-Native Systems, Not Retrofits
The temptation when modernising government technology is to retrofit. That instinct is exactly what Africa cannot afford.
The Hidden AI Infrastructure Gap in East African Universities
Faculty want AI in the classroom. IT departments don't have the data plumbing to deliver it. Here's the gap nobody is funding.
Building Government-Grade AI in Uganda: 5 Lessons from the Field
Procurement compliance. Stakeholder management. Data sovereignty. Local language requirements. Long-term maintenance planning.
Want this applied to your organisation?
Send us the decision you are trying to make. We reply with a scoped quotation.
Most quotations answered within one business day.